Showing posts with label banks. Show all posts

27 August 2009

Eamon Gilmore calls again for the temporary Nationalisation of Ireland's major Banks

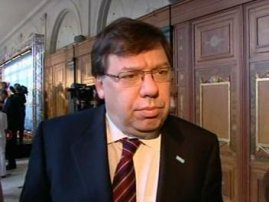
Eamon Gilmore (photo), leader of Ireland's Labour Party, has again called for the temporary nationalisation of the country's main banks "as an alternative to the setting up of the government-proposed National Asset Management Agency (NAMA)".

Speaking on RTÉ News, Gilmore said that "a mechanism should be established to write down bad debts, before returning the banks to the market when they are restored to good order".

The Labour Party leader also emphasised that "it is a necessity to get the banks lending to businesses again".

His proposal was not without cost, Gilmore added, but he claimed it would mean a lot less risk for the taxpayer than the government's plan.

Under the government's proposed legislation, NAMA would be taking over € 90 billion worth of debt away from Irish banks, so that they can start lending again.

The amount NAMA would pay for the debt has yet to be decided. But in an article, published in yesterday's edition of The Irish Times, 46 economists warned that NAMA might pay too much and thus create an extra burden for Ireland's taxpayers. (see yesterday's entry below)

Fine Gael has already stated that it will oppose the government's NAMA plan when the Dáil debates the legislation next month. Since Sinn Féin, which demands a referendum on NAMA, is against it as well, this means that all opposition parties in parliament are united on the matter, even though they do not agree on the details of possible alternatives.

The Green Party, who is the junior partner in the government coalition, will hold a special conference to debate the plan. (see my entry of August 25th)
The outcome of this conference is far from certain, and neither is the continuous support of the Green Party for the current government.

As things stand at present, anything is possible. A temporary nationalisation of our major banks - as demanded today and previously by Eamon Gilmore and his party, as well as by Sinn Féin and the Socialist Party in separate statements - would in my opinion be the safest and least costly option.

We can expect that the government will not listen and stick to its original plan. So I suggest that now is a good time to contact your local TDs, especially those from Fianna Fáil, and tell them in no uncertain terms what you think of NAMA. It might also be helpful to mention that their own seat will be in serious danger if they ram through a legislation that no one in the country really wants, but for which everyone would have to pay severely over decades to come.

The Emerald Islander

26 August 2009

Economists warn Ireland's Government of the "economic folly" to create NAMA as planned

A group of senior economists has urged the Irish government to reconsider its approach to the planned National Asset Management Agency (NAMA), saying that "not to do so would be economic folly".

The 46 academics, including ten professors, have entered the debate on the future of Ireland's economy in general and NAMA in particular with an article that is published in today's edition of The Irish Times.

The group of economists argues in the article that "alternatives to NAMA are possible" and there are "a number of other ways to lay the ground for a healthy banking system".

The experts say that - in its current form - NAMA "commits the State to overpay for troubled bank assets". Instead only the current market value for assets (ca. € 30 billion) should be paid, and not 'optimistic' higher values envisaged under NAMA. This would leave the banks in need of more capital, and more of it should come from bondholders and shareholders of the banks.

The government's advisor Dr. Alan Ahearne has disputed a number of the group's claims and criticised its arguments. But when one has the choice between the arguments and 'expertise' of the current government, which created the crisis and has nothing to offer but incompetence on one side, and a group of 46 well-known, established and experienced economists on the other, I know whom I trust and listen to.

The Emerald Islander

29 May 2009

First Fall in Irish Mortgages since 1990

Ireland's property market is in stagnation as house prices are falling steadily (see my entry of May 27th) and most people have neither the money nor the will to buy property at this time of economic recession and financial insecurity.

The latest monthly statistics from the Central Bank of Ireland show now the first net fall in mortgage lending since 1990.
The bank's figures for April 2009 confirm that the Irish property market has slowed to a trickle, and in some parts of the country it has dried up completely.

It is the first time that repayments on existing mortgages have been greater than new mortgage lendings since the Central Bank began this monthly statistics series in 1990. Overall, mortgage lending fell by over € 100 million last month.

The amount of money lent out in the rest of the economy also fell, reflecting concerns raised by many business groups about their great difficulties of accessing credit, or even normal business overdraft facilities to maintain proper cash flow.

The Central Bank's statistic also shows a sharp fall-off in credit card spending. The amount of money Irish consumers spent using their credit cards in April was € 180 million lower than in April of last year.

13 May 2009

ISME: Irish Banks not open for Business

More than half of Ireland's small and medium-sized companies have been refused credit by Irish banks in the first three months of this year.
The vast majority of these firms were not looking for large loans or long-term credit, but for the normal over-draft and short-term credit facilities usually available to established businesses.

A nation-wide survey, conducted by the Irish Small & Medium Enterprise Association (ISME), shows that 58% of existing and viable businesses were refused regular credit by their banks between January and March 2009.

This figure is up ten points from the 48% recorded in the last Bank Watch survey, which was published in February. (To put this into perspective: Only a year ago the figure was just below 20%.)

83% of Irish companies said that banks were making it more difficult for small firms to get access to finance. More than half of the companies surveyed have been with their bank for ten years or more.

ISME chief executive Mark Fielding says that the Irish government should "stop pussyfooting around with the banks and force them to free up badly-needed credit".

He points out that the survey's findings are clearly at odds with various public statements issued by Irish banks, saying that they were "open for business".
"Recent initiatives and full-page ads taken out by banks in national newspapers were nothing more than PR stunts," Fielding added. "As far as the Irish small and medium-size companies are concerned, the banks are not open for business."

If this unacceptable behaviour continues, more Irish businesses - most of them sound, viable and well-established - will be forced to cut jobs and, eventually, to close.

Not enough that the banks created our financial crisis in the first place and turned Ireland from boom to bust within a few short months. No, now that the government has guaranteed their existence and bailed them out with billions of taxpayers' money, they become really nasty.

Instead of using the money from the re-capitalisation to stimulate the Economy and provide small and medium-sized businesses with normal credit and cash-flow facilities, Ireland's banks - especially AIB, Bank of Ireland and permanent tsb - are now hoarding money like never before.

If it needed any further proof, this is clear evidence that the banks are no longer part of the normal business environment, and certainly not the "cornerstones of our Economy", as the government and Fianna Fáil keep telling us again and again.
Banking has become an immoral activity, geared only towards the banks' interests and with absolutely no regards for other businesses, for individuals, the Economy or the nation as a whole.
I think we should stop calling them banks, and refer to them in future as 'pigeons'. Because like these parasitic birds the bankers want to be fed when they are on the ground, but when they are up in the air again, all they do is dropping excrements on all of us.

The Emerald Islander

29 April 2009

A Nation of Debtors and Fools

Today the Central Bank of Ireland has stated that "the number of people in personal debt is growing rapidly", and that this is being "driven by mortgage borrowings".

At an Oireachtas Committee meeting in Leinster House this morning John Kelly, the Head of Statistics at the Central Bank, declared that "the number of people in debt in Ireland is rising faster than in any other Eurozone country".

According to Mr. Kelly "the number of people in mortgage debt is three times higher in Ireland, compared to other countries in the Eurozone". He also said that the large number of mortgage holders on variable or tracker rates is positive.

Separately, the number of people presenting themselves at the offices of the Money Advice Budgeting Service (MABS) has increased substantially since 2006.
Ann Marie O'Connor of MABS told the Oireachtas Committee that the amount of debt people are in who attend the service is also increasing. She said that her organisation was also concerned about the tactics of some debt collection agencies.

Mary O'Dea from the Irish Financial Services Regulatory Authority said a code was now in place to offer some protection for people in mortgage arrears. But this code was criticised as not going far enough by the representatives from the Free Legal Advice Centre.

What does all this information tell us?

Well, it presents us - the people of Ireland - with the blunt and uncomfortable truth that we (or at least the majority of us) have been living well beyond our means during the years of the false economic boom dubbed the 'Celtic Tiger', which was - as we now know - nothing but an artificial bubble, created by irresponsible politicians and greedy bankers, property developers, builders and estate agents.

As much as our collective anger is now directed at these people (and with all justification), we have to accept the fact that most of us were not innocent victims of the greedy buggers in suits. The vast majority of Irish people was only too willing to go along, up the metaphorical garden path, leaving all common sense and responsible behaviour behind.
We were carried away by the idea that we - little and long-suffering Ireland that was always poor and exploited by others - had now at long last found the legendary pot of gold at the end of the rainbow. We were rich, really rich, we thought.
And instead of being happy with that and building a nice nest egg for an even better future, we fell collectively for the many temptations a bunch of criminals and gamblers put in front of us.

People on modest incomes, who had been happy living in a normal house, driving a normal car and going on holiday once a year, felt 'entitled' to have a lot more. So they bought a bigger house, or even two. Some even acquired an additional apartment abroad, in places like Spain, Portugal or even Bulgaria. The latter is a country without proper political structures and widely controlled by the local version of the Mafia, a group of gangs recruited mostly from the former Communist security service (Bulgaria's version of the KGB).
How on Earth would anyone even think of buying property in such a place?!

But Irish people did. Quite a lot of them, in fact. They also 'needed' a new and much larger car, preferably one of the most polluting and environmentally unfriendly four-wheel-drives known here by their American name SUV (Sports Utility Vehicle).
And not enough with that, they also had to go on exotic foreign holidays several times a year, and to keep up with the Jones' also on additional luxurious 'city breaks' to various continental places over the weekends.
And if there was not enough money in the bank to pay for all this, then they used their various credit cards. The bank would always offer more loans, new cards and many 'lucrative refinancing packages' if someone got really strapped for cash.

There is an old saying that a fool and his money are easily parted. Ireland is the living proof that this phrase is still correct.
It gives me no pleasure to say this, but the Irish have now been exposed to the whole world as a careless and feckless wannabee nation, made up of irresponsible and greedy fools, gangsters, fraudsters and drunken yahoos.

Some of us - for example David McWilliams, George Lee, a few other people with common sense and even yours truly - warned of the consequences of the financial madness and wrote page after page and column after column, but to no avail.
We were called "spoilsports", "party poopers" and "eternal pessimists" by the punch-drunk financial criminals, and completely ignored by most of the 'ordinary' people.

And even now, that the metaphorical cat is well out of the bag, there are thousands of fools in this country who cannot or will not see and accept reality. Unfortunately this group is led by our government, the worst bunch of wasters and incompetents ever assembled in the history of the state. And since ignorance still rules the roost, things will get much worse throughout this year, next year, and perhaps for many more years to come.

There is only one way Ireland can regain strength and stability: We need a new government, urgently, and a reform of our political and electoral system. Everything else will follow from that. As long as we keep the current lot and our completely broken 19th century system in place, nothing we do and no remedy we offer the economy will be of any use.

The Emerald Islander

20 February 2009

AIB has Egg on its Face

The Allied Irish Bank's regional office and main branch in Cork has egg on its face - literally.

Three days ago - on Tuesday, February 17th at about 11.30 am - a "well-dressed man", wearing a suit and tie, approached the AIB's main building on the South Mall in Ireland's second-largest city. He carried a medium-sized cardboard box, and at first it appeared as if he was just another customer, walking towards the bank.

But then he stopped in the street outside the impressive 19th century building (photo below), opened his box and began to throw eggs at the façade and windows. The bombardment lasted only a few minutes, but it brought traffic to a halt on the usually busy South Mall, one of Cork's major inner city streets.
Some of the motorists and various passers-by are reported to have given the unidentified man a spontaneous round of applause.

The AIB building at 97 South Mall, Cork is probably the most beautiful and impressive bank building in Ireland. Built in 1825 and reconstructed 1863-65, it was the first branch office of the Irish Provincial Bank Ltd., which later became part of the Allied Irish Bank Plc (AIB). Thus it is particularly iconic among Irish banks and a clear symbol of traditional banking and old-world capitalism.

After finishing what he had come for and using up all the 'ammunition' he had brought along, the man dropped the by now empty box and walked away from the scene as inconspicously as he had arrived.

The box, which had been filled with three dozen Irish farm eggs, was later identified as an item bought from a poultry merchant at the nearby 'English Market', Cork's very popular traditional grocery market.

However, the identity of the "well-dressed man" and the specific motives for his direct action remain so far unknown.

An AIB spokeswoman confirmed the incident and declared that the bank would not be making a complaint to the Garda (Ireland's police).
"The man did not enter our building," she said, "and we have no idea who he is, or why he has bombarded the bank with eggs."

While the identity of the 'Egg Man of Cork' might well remain a mystery, with regards to his motives one can think of many. The outrageous behaviour of Ireland's major banks, including AIB, whose reckless and irresponsible management has created the most serious economic and financial crisis in the history of the state, is causing widespread anger among Irish people.
Especially the fact that most of the over-paid fat cat bankers are unwilling to admit their mistakes, expect to remain in their posts and receive their salaries of several million Euros per annum as if nothing has happened, creates great resentment among many ordinary people, whose tax money is used by the Irish government to bail out the failed banks.

I suggest that we all pause for a moment and give three cheers to the 'Egg Man of Cork'...

The Emerald Islander

19 January 2009

And some good News coming through as well...

In my earlier entry from this afternoon I mentioned that some statisticians regard January 19th as "the most depressive day in the whole year" and indeed plenty of people obliged to make it so. In particular the stock brokers in Dublin and London, who sent the financial markets - but especially bank shares - down into the proverbial cellar.

Despite reassuring words from both governments - in Dublin and London - the world's financial dealers no longer trust us and the value of Irish and UK banks plummeted to another all-time low.
The hurried and quite shambolic nationalisation of Anglo Irish Bank by our government was fuelling the fires of distrust instead of sending the - intended - message of stability and 'business as usual'.
And in Britain the announcement of further billions of taxpayers' money being pumped into the sinking banks did not help them a bit. Quite the opposite. Many international finance houses, especially the cash-rich ones in the Far East on whose willing to lend we now depend more than ever, regard us with great suspicion. Subsequently UK bank shares fell by 68% today, losing over two thirds of the little value they now have in one single day!

The combined forces of government ignorance, regulators' laziness and sleeping on their watch, and bankers' criminal greed have holed both Britain and Ireland in a serious way well below the waterline.
The question by now is no longer when we can stop the ships sinking, but if we can stop them at all.

But even on this "most depressive day in the whole year" there is a little bit of good news as well. Five more directors from the disgraced board of Anglo Irish Bank have today announced their resignation from the board, in order to "make room for a new leadership team".
And not a moment too soon. In my opinion their resignation comes actually quite late, and I have not the slightest bit of empathy for these reckless bankers. They are responsible for the biggest financial and political crisis since the 1930s, and if I had the power, I would send them all to jail and throw away the keys...

An even better piece of news is that Brian Goggin (photo), the Bank of Ireland's highly incompetent chief executive, is stepping down as well.
The bank announced today that Goggin will retire this summer, a year earlier than planned. The bad news is that by retiring - instead of being sacked for the massive failure he presided over - Goggin will get his full pension, a golden parachute and many other perks he does not deserve and has not earned.

A man who presided over the collapse of a major bank that lost 95% of its value in less than two years deserves to be sacked, flogged and made to pay for his disastrous lack of leadership.
But as corrupt as our system is, this is unlikely to happen. Brian Goggin will go home as a multi-millionaire and enjoy a jet set lifestyle for the rest of his days. The bill for his folly will be paid by us - the Irish tax payers. But given the fact that for more than a decade a majority of us has persistently elected the most incompetent politicians to government again and again, we deserve nothing else. (And anyone who will in future vote for Fianna Fáil or the Green Party deserves that things get a lot worse than they are already...)

I suppose we should be content with the good news that five of the main gangsters from Anglo Irish are gone and that the arrogant fool Brian Goggin is following suit soon. All in a day's work, and not so depressing after all...

The Emerald Islander

The most depressing Day in the Year

This morning someone on the radio made the remark that January 19th is - apparently - "the most depressing day in the year". How they come to that conclusion I do not know, and it was not really explained on the programme either. These days many radio presenters have the habit of throwing in comments, remarks and statements that they have neither researched nor cross-checked.
On the other hand, there are countless statistics nowadays, about anything and everything. So it is quite possible that there is such a statistic and that it puts a black mark on this day - January 19th.

Whatever is the case, the stock brokers in Dublin must have been listening to the programme this morning. And they took it very seriously and decided to contribute to the day appropriately. Subsequently the value of Irish bank shares has dropped to another all-time low.
As I write this, shares in Allied Irish Bank (AIB) dropped by almost 52% to 70 cents, after slumping as much as 60% earlier. Bank of Ireland is down now 20% to 60 cents per share, which is already a recovered value from earlier falls of 47%. And Irish Life & Permanent, who own the permanent tsb bank, tumbled 32% to € 1.49.

Today's falls come in the wake of market suggestions that Bank of Ireland and AIB look unlikely to be able to raise extra cash from private investors to top up a proposed state investment in the banks.

It appears that a statement I made on the BBC's "Any Questions?" programme more than seven years ago was quite correct, and every day this becomes more obvious to everyone.
What I said - back in September 2001, shortly after the airborne terror attacks on New York and Washington - was this:
"It becomes quite clear that conventional capitalism as we know it does no longer work. There are people on this planet who - for whatever reason - no longer want to live and work, inspired by the chance to gain wealth and personal comfort, but prefer instead killing themselves, if they can do serious damage to the capitalist system in the process. This means that no business and no organisation that follows the traditional capitalist system alone will be save and successful in future."
There might well be people who heard my statement then and made changes to their lives and to their business, as I did myself. But the vast majority did not. In fact, here in Ireland the small class of really wealthy people took no notice of it at all, as they have never listened to anyone 'on the outside' ever. They just think that their wealth gives them complete immunity from the rest of the world.
For the past ten years they created an artificial bubble of social and financial illusions that puts the well-known story of The Emperor's New Clothes well into the shadows. In the process they have not only done great damage to themselves and their companies, but to the Irish nation as a whole. Now chicken are coming home to roost on an almost daily basis, and there is for now no end in sight.

As this is supposed to be "the most depressing day in the year", I will oblige and make another statement on this matter.
Not only does conventional capitalism as we know it no longer work in the face of fundamentalist terrorism that has no concern for human lives, it does also no longer work in a globalised world that allows banks to create and gamble with artificial money that does not exist, never will exist, and has no relation to any real values.

For thousands of years people used raw materials, produced something other people wanted, and sold it to them for a price higher than the costs of production. That way they made a profit, and this is the core of old-fashioned capitalism.
Nowadays more and more manufacturing - even the production of the most basic goods - is "outsourced" to low-wage economies, mostly in the Far East. Meanwhile here in the West our apparently so bright and clever people find it more suitable to concentrate on 'financial services', which means in plain English gambling with other people's money and getting paid huge bonuses for it, just like in any casino in Las Vegas. What they really are is not bright and clever at all, but greedy and stupid

If we keep this up and do not learn our economic lessons very quickly, capitalism in any form will cease to exist. Private enterprises and public services alike will collapse, and Ireland - together with many other countries, especially in the English-speaking world - will encounter a period of absolute anarchy, violence and destruction. What ever will emerge from that after some time is anyone's guess and unpredictable, even for someone with a good track record of correct predictions.

There is still time to get things right, but not a lot of it is left. Money and time are literally running out for Ireland. The only way to turn things around is a radical change of direction, under a strong leadership.

Well, perhaps that researcher quoted on the radio this morning was right after all and this is the most depressive day of the year...

The Emerald Islander

15 December 2008

€ 10 Billion Rescue Programme for Irish Banks

The Irish government has announced its support for a massive recapitalisation programme of up to € 10 billion for some of the most battered credit institutions in the country.

A statement from the Department of Finance says that its objective is "to ensure the long-term sustainability of the banking sector in Ireland".
The government will support the programme "alongside existing shareholders and private investors", and it will "underpin its contribution through the availability of credit to individuals and businesses in the real economy".

That sounds rather positive and gives some hope for the Irish economy, which is not only in recession, but also mismanaged by an bunch of third-rate people whos - meanwhile only too obvious - incompetence is only matched and even outshon by their self-serving arrogance and greed.

After long meetings with bank executives the Minister for Finance Brian Lenihan (left) confirmed that money from the National Pensions Reserve Fund will be used for the new recapitalisation programme.
State investment will take the form of preference and/or ordinary shares in the institutions receiving funds, which means in fact a part-nationalisation of our major banks.

Lenihan said that State investment would be "assessed on a case-by-case basis" and all the institutions in question were being asked to submit their proposals by early next month.

A spokesperson for the Allied Irish Bank (AIB) said that the bank's board would "discuss the government announcement" when it meets later this week.

There has also been a special Cabinet meeting today, in addition to the regular meeting on Tuesday.

The Irish Business & Employers' Confederation (IBEC) has welcomed the announcement on recapitalisation.
The group's Director General Turlough O'Sullivan (right) said that "the banking sector is vital to the effective functioning of business and the economy generally".

And he is right, of course. But there remains the so far unmentioned large elephant in the room, whom neither the government not IBEC seems willing to tackle.
I am talking about the people who are fully responsible for the crisis, the chief executives and board members of the banks and building societies, who created the huge financial bubble and then let it burst without any concern for their own institutions or the nation as a whole.

If these people remain in their well remunarated - in my opion highly overpaid - positions, we can as well take the € 10 billion to the cliffs of Moher and throw them into the sea. Everyone can see the dimensions of the crisis now, and everyone agrees that only drastic measures will make a difference, save the banks and restart the economy. But it will only mean throwing in a lot of good money after plenty of bad debts if the creators of the problem are allowed to stay in charge.

The Minister for Finance must insist on the resignation of the entire boards and the chief executives of the failing banks. And should they refuse to do so, he must use his authority and remove them by force.
Only with such a clean sweep of the boards the way will be free for new and inspired leadership that can do things differently and give us hope to come out of the crisis in a reasonable time frame.

We need also to remember that the € 10 billion now offered by Brian Lenihan come from the National Pensions Reserve Fund, which is limited in seize and supposed to guarantee our future pensions. This is not money we can freely and easily use for speculations and gambling.
Only two weeks ago it emerged that there could be a deficit of between € 20 and € 30 billion in our pension system (see my entry of November 30th), which is not yet fully investigated. If we now give € 10 billion of pensions money to the banks as recapitalisation fund, we need to be sure that this money will come back - and hopefully with interest and some profit - and not be lost like the many billions the banks and their incompetent executives squandered in recent years.

Only a radical change in management and policy can secure that. No matter how much of our money the government will pump into the financial institutions, it will only do them some good if the lost confidence in the banks is restored.
With all the old duffers who were either too greedy, too ruthless or too incompetent (and in some cases all three combined) staying in their cosy jobs, there cannot be any confidence-building.

One of the main elements of the crisis is that banks are now refusing to give loans to each other.
Have you ever wondered why? Well, the answer is simple enough: Because they don't trust each other. The people who run our financial system make a relatively small group, and they all know each other only too well. And since they don't trust each other any longer - and for very good reason - it is clear that they have to go. How can the government and the general public have confidence into bankers who are no longer trusted by their peers?

Money is only one element of banking. The second - and way more important - is trust. And that is worth a lot more than € 10 billion, it is in fact priceless. I urge Brian Lenihan not to forget this and to make sure that our money is only injected into the banks after they have cleaned up their management structure.

The Emerald Islander

21 November 2008

Speculations fly high after Lenihan's Bank Talks

Bank of Ireland has today confirmed that it has been "approached by a number of parties interested in investing in the bank".

This news comes after reports that a major consolidation of Irish banks has emerged as a possible solution to the current crisis.

Last night RTÉ News reported that talks between Minister for Finance Brian Lenihan and bank chiefs had led to the possibility of a radical overhaul of the Irish bank system. (see also yesterday's entry on this subject)
This led to speculations about what shape this would take, and whether foreign or private equity investors would be involved.

Bank of Ireland shares, which had already climbed this morning, were up almost 25% at € 1.26 just after the statement.

Meanwhile the Group Chief Executive of Allied Irish Bank (AIB) has declined to comment at all on the situation.
Arriving at a posh function in Dublin, Eugene Sheehy (right) said that "shareholders read what they read, but we [the bankers] have no comment to make".
It is really mind-boggling how smug and arrogant Sheehy still is, after having lost 95% of his company's value since he took charge of it in 2005 and having to go now to the State and to us - the taxpayers - cap in hand...

Asked if he could see a situation where there would be only two large banks operating in the Irish market, he responded that was speculation.
Which, of course, it is, cooked up by some financial journalists in Dublin who pretend they can read the mind of Brian Lenihan.

Yesterday's talks involved a series of meetings at Farmleigh (the government's official 'guest house' in the Phoenix Park in Dublin) between Lenihan and senior executives from the financial institutions covered under the State guarantee scheme. (see yesterday's entry)

Since the guarantee was given in September, the Minister for Finance has the power to force mergers between financial institutions. This is one of the concessions the troubled banks had to make before the State was willing to cover them.

After the meetings some participants 'believed only Bank of Ireland and AIB would remain after the shake-up', but there has been no comment on the content of the meetings.

Brian Lenihan (left) said that yesterday's meetings were "focused on ensuring there would be adequate credit for Irish businesses".

The suggestion of a major wave of consolidation would also have to be linked with fresh capital for the banks.

There is, however, still no clear picture of how a final deal would be put together, or how long it would take.

I suggest that the nervous crowd of Dublin's financial journalists stop speculating and second-guessing other people, shut their laptops for a couple of days, relax and have a few pints. As the pressure of the world markets weighs heavily on our banks, Brian Lenihan will have to come up with a solution soon. He knows that, the banks know it, and we all know it.

And when he has made his decision - which is his, and his alone by the power of his office - then we can start analysing and commentating. I hope Lenihan will do a better job with the banks than he has done with the 2009 Budget. And personally I also hope that we will in the end have more than just two banks left in this country. I have never trusted the Bank of Ireland, nor the AIB, and never was a customer of theirs. And if these two - as some people suggest - would remain alone in the field of financial services, we all would be forced to do business with them. I would not feel comfortable with that at all.

In fact, mergers and amalgamations that create ever larger banks are in my opinion not the answer to the current financial crisis. The larger a bank is, the more dominant and arrogant it tends to be, and the more it will also be enticed to participate in the massive internatinal gambling that brought all the big western banks into the trouble they - and subsequently we all - are in now.

I would go in the opposite direction and break up the largest banks and create a number of new small regional banks, whose regulations would limit them to traditional banking activities and ban them from participating in the international speculation and gambling operations. They should be staffed by local people and have an actively positive approach towards small and medium-sized businesses, as well as to idividual customers.
This could and would restore the confidence and goodwill the whole Irish banking sector has lost over recent months, and would also stabilise and stimulate our ailing economy.

The Emerald Islander

20 November 2008

Brian Lenihan is meeting Irish Bank Executives to sort out the ever more serious financial Crisis

Today chief executives from the six Irish banks and building societies that are covered by the State guarantee scheme have separate meetings with Finance Minister Brian Lenihan (right).

The series of these one-to-one confessional meetings comes in the wake of the Price Waterhouse Cooper report on the future debts and capital requirements for the six Irish financial institutions covered by the scheme, which was announced by the government in September.

The participants in the talks might be especially cautious, as world markets have once again tumbled, following sharp overnight losses on Wall Street, prompted by a fresh wave of jobs cuts in the USA and another gloomy economic outlook.

But - amazingly - Irish bank shares are among the very few that are rising today. However, one should not forget that on Monday and Tuesday of this week they were hitting rock bottom, with both Bank of Ireland and Anglo Irish Bank shares falling below the € 1 mark for the first time ever. On Tuesday Bank of Ireland shares were even close to 80 cents for a while, and I suppose they could not fall much further without the whole business imploding completely. And - as we have seen in recent weeks only too often - short-term gains on the world's stock markets are often followed by further drops in value.

Today's rises are mainly on expectations that the government is edging closer to a refinancing deal for the nation's main financial institutions.

Earlier this week the Taoiseach had told the Dáil that "the often mentioned recapitalisation of banks alone will not solve the issue of access to credit for small businesses".

During leaders' questions Brian Cowen (above left) said that the government was "looking at a range of measures to remedy the liquidity problem", but he was "constrained in revealing what they are at this time". This was another fine example of procrastination in true Offaly style.

Under the bank guarantee scheme, Cowen stated, all covered banks were drawing up business plans, and this process was now "at an advanced stage". He also announced that the Financial Regulator had received a draft report on the banks from the consultants Price Waterhouse Cooper.

Today the government expects to receive the full business plans from the financial institutions.

Brian Cowen said that if these plans did not contain measures to provide adequate lines of credit to businesses, they would be rejected.

Labour Party Leader Eamon Gilmore (right) declared that the government sounded "like helpless bystanders", while Fine Gael Leader Enda Kenny demanded that the banks be recapitalised.
He reminded the Dáil that 10,000 Irish jobs were being lost every month as small businesses got squeezed.

Meanwhile the International Monetary Fund (IMF) has approved a loan of more than $ 2 billion to Iceland, to help it cope with what has been described as "a banking crisis of extraordinary proportions".
The government of Iceland had asked the IMF for help after its banking system collapsed within hours last month. Let's hope that Ireland will be spared such a traumatic experience.

The Emerald Islander

19 November 2008

Citibank reduces Staff by 20%

The large US financial group Citibank has announced plans for about 52,000 new job cuts, on top of 23,000 redundancies already made this year. This makes a total of 75,000 job cuts in the organisation and represents a staff reduction of about 20%. About 300,000 jobs worldwide will remain in the bank "in the near term".
According to a spokesperson, the job cuts will come "from redundancies, the sale of units and natural wastage".

I cannot help but wonder what any bank needs 375,000 or even 300,000 (well paid) employees for, in an era when most of the world's money is electronic and only exists virtually, when stock market trading is computerised and automated - with pre-set cut-off points in case of extreme price drops - and when the number of traditional branch offices is at an all-time low (which is the case with all banks, not just Citibank).
The service staff in those branches also seems to get ever younger, which means two things: less experience and less pay. Personally I think that the overall very young age of bank service and trading staff is partly responsible for the current crisis.

A year ago, Citibank (with its huge and glamorous head office in New York) was the largest bank in the world. But how different things can be within a few months shows today's financial bulletin.
From being a world champion, Citibank dropped to 7th place in the international ranking, where four of the five largest banks in the world are now Chinese.

Citibank was established in 1912 as the City Bank of New York by a number of - mostly Jewish - merchants under the leadership of the former US Postmaster General Samuel Thompson.
After going through changes in ownership, the bank established its presence as the USA's largest bank in 1865, and soon it became the first US bank to set up operations overseas. Mergers and acquisition followed and the bank could only grow larger and larger.

However, the bank's many international engagements created a lot of criticism, and it was also blamed directly for "having played a major role in the Wall Street Crash" of 1929. Four years later, in 1933, Senator Carter Glass said during an investigation into the financial markets that the bank's then president Charles E. Mitchell "more than any 50 men is responsible for this stock crash".

More recently the group has faced one of the toughest economical periods, with the weakening US economy and the collapse of the 'subprime' mortgage market the main reasons for trouble.
In fact, much of the crisis was actually created by Citibank itself (again), as it was one of the main instigators of the 'subprime' mortgage market and one of the largest lenders in it.

Meanwhile Citibank has lost more than $ 20 billion in the past year and the bank's chairman and CEO Charles O. Prince III (left) had little choice but to resign in disgrace and rather hastily a year ago.
(He will, however, enjoy a comfortable retirement, as he left Citibank with a 'golden handshake' of $ 38 million in personal compensation.)

Citibank has reported four straight quarterly losses and some analysts believe the bank will not make a profit again until 2010.

Of the 52,000 newly announced job losses, about half are understood to be accounted for already, with the recently announced sale of Citibank's German retail banking business and the closing of an Indian outsourcing operation.
It is expected that the remaining 25,000 jobs will be gone by the first half of 2009, but Citibank declined to comment on the cuts.

"Underlying business remains strong and revenues have been stable," a spokesman said, adding that its capital position was also "very strong". However, business analysts and share prices tell a different story and I wonder if it is a general requirement for a banker to be a habitual liar, or if it just helps to do the job.

The share value of Citibank has dropped again by 6.2% after the announcement. It is down almost 70% since last year, and the bank's new chief executive Vikram Pandit has come under pressure from critics who have doubted his ability to turn around the company and weather the financial crisis.

However, Citibank is probably quite safe, as it is one of the nine financial institutions benefiting from the US government's bail-out programme.
The US Treasury announced last month that it would be providing cash injections worth $ 125 billion for the troubled financial sector, to be shared between Citibank, JP Morgan Chase, Bank of America, Goldman Sachs, Morgan Stanley, Wells Fargo, Bank of New York Mellon, State Street and Merrill Lynch. (And as soon a the announcement was made, Goldman Sachs paid $ 17 billion in 'bonuses' to its senior managers. One wonders what this was for. Perhaps a bonus for having successfully conned the clueless Bush administration into handing over even more billions of taxpayers' money...)

The Emerald Islander

12 October 2008

In Reply to David McWilliams

This morning David McWilliams (right) published another very interesting article on his website.
You can read the complete text by going to http://www.davidmcwilliams.ie/2008/10/12/breaking-the-vicious-circle

In this article David suggests the establishment of a new international clearing house for banks under the direct authority of the G 7 (most industrialised) countries, which are the USA, Canada, Japan, the UK, France, Germany and Italy.

Once again I happened to be one of the first people to read the article, and the first to leave a comment at 5:58 a.m. this morning. Having read my comment, which was written impromptu and without preparation, a second time now, I realise that it is not just a comment on David's article, but goes further with its demands and is a separate article itself.

I am taking the liberty of posting it here as well, for the benefit of those who do not read David's articles or visit his website on a regular basis. So, here is the text:

Events in Ireland - and in most other countries - have been overtaken by the international reaction - or perhaps over-reaction - to the US credit crunch.

A new international clearing house under the control of the G 7 would be useful, I agree. But we need a lot more to get the economic fleet sailing again. State pressure on the banks will be necessary, yes, but at this stage one has also to contemplate a complete nationalisation of the whole banking system.

We were very kind and generous to the banks by giving the guarantees, but it seems to have little affect. The problem is that leopards do not change their spots. So they try to carry on, perhaps with reduced speed, but still staying on the same old course. This has to stop.

If we put all our money and state resources up, then I think we should also have control. And that means first of all a change of course and of leadership. Heads need to roll, quite a lot of heads, and from the top downwards. Most of the CEOs and directors have shown their incompetence and recklessness only too clearly, so they have to go - fast and without golden parachutes.

There should be a new rule that no-one in any company - including banks and stock brokers - can earn more than ten times the income of the lowest paid employee. This would lead over night to a massive increase in equality, and also lead to more investment.

Simultaneously Brian Lenihan should raise the income tax for all people earning more than 100,000 per annum significantly, and introduce new taxes on the buying and selling of shares. Betting taxes should be raised as well, and all the loop holes for the super-rich should be closed immediately.

Further the government should - through the budget - impose an immediate freeze of all consumer prices (especially for food, fuel, electricity and all essential commodities) for at least six months. This would be a great relief for everyone, but particularly for people with lower income, and get us well over the winter. The freeze should be reviewed in 6 months, with the option of an extension.

In terms of structure, all the various regulators should be abolished and merged into one single national consumer authority, directly responsible to the Taoiseach, and with real powers and teeth, as they are in existence already in many continental countries. This would reduce state expenditure and strengthen the effects of regulation.

IDA, FÁS and other institutions should focus on supporting existing Irish businesses and helping to start new enterprises - especially small and medium size companies - in Ireland and owned by Irish people. It has been one of the main mistakes to concentrate always on the big international companies - mostly US owned - and give them millions in advance of even coming and creating jobs. They all packed up again when the extra benefits ran out, or when they got better offers elsewhere.

In general Ireland and Europe should reduce their economical and financial ties with the USA as much as possible. The USA have created this crisis, out of greed, stupidity and criminal activity, and now the whole world is suffering as a result. We have to be realistic and look after our own interests first. (As the Prime Minister of Iceland said so rightly last week: Every man for himself.)

Fortunately we are not entirely on our own and have the EU and ECB behind us. If Europe uses her very well developed infrastructure and skill base, the recession will not last as long as is feared now, and it will also be manageable. Let the USA sort out her own mess, which is entirely of her own making!

Europe could come out of this crisis a lot stronger, and become the No. 1 economic power in the world, if we do things right. Otherwise we will always depend on whatever the USA is doing.
Let the Americans sink or swim, whatever they can manage. Their country is meanwhile so run down - in all areas - and riddled with social and political problems that have no relevance for us.

I am no socialist as such, and as we have seen in Eastern Europe, most socialist models have failed as well. But we need to realise that capitalism of the US & UK style, which has so far been our model as well, does not work. It has its failure already built into the system. So if we repair the damage, only to return to the old capitalist model, we can as well leave it and save us the bother and money.

There are very good and workable models of moderate capitalism with a social dimension, especially in the Scandinavian countries, but also in Germany, France and some other nations. These models we need to study closely, and then adopt which ever is the most suitable for us. If we do that, we will have a safe and prosperous future. If not, we will be sucked down into the abyss by the vortex created by the foundering last empire - the USA.

The Emerald Islander

06 October 2008

Another Black Monday

The world's financial markets have been in a deep crisis for weeks, but today they are in panic.

No other word fits the massive turmoil, chaos and running-about like a bunch of headless chicken. There have been heavy falls on stock markets everywhere, with many exchanges hitting record lows and seeing big sell-offs of bank shares.

Analysts are blaming a lack of certainty about US and European rescue initiatives for the financial sector.
That is quite correct, but it only exposes the high rollers in the world's banks and financial institutions as the incompetent and greedy fools they are.
These brainless wreckers of the economies of many countries, who are unqualified for the overpaid jobs they hold, should be rounded up by the police, interned and charged with collective fraud and high treason.
And the governments of their countries should strip them of every personal asset they have accumulated through their criminal machinations which have pushed the world into the biggest crisis for 80 years.

If you think that I am angry about all this, you are quite right. I am very angry.
And if you think that my suggestions would be an over-reaction to what happened - well, this might be. But if we let these white-collar criminals get away with billions of looted money while we all have to suffer as a result of their enormous blunder, the same thing will happen again in some years from now and no-one will have learned any lessons.

Poor people who steal some food from a super-market are sent to prison. Perhaps rightly so.
But the real criminals who wreck whole nations get - so far - away free and can even keep all their ill-gotten gains.
If we let this happen, we deserve every bit of hardship and suffering that is coming to us.

Today will probably enter the history books as another 'Black Monday'. Despite the more than generous (and in my opinion outright foolish) bail-out programmes that many governments - from Ireland over Germany and other EU countries to the USA - have hastily put in place to save the rotten banks, the international money markets seem to know better. Just have a look at today's reports:

DUBLIN:
The ISEQ index closed nearly 10% lower, with shares in the four main financial stocks falling sharply. Irish Life & Permanent and Anglo Irish Bank were more than 20% lower.

NEW YORK:
The Dow Jones index fell below the key psychological level of 10,000 for the first time since October 2004. It lost as much as 800 points, but recovered later, to close down 'only' 3.3% (340.49 points) at 9,984.89.
The high-tech dominated NASDAQ index fell 4.34% (84.43 points) to 1,862.96.
The Standard & Poor's 500 index lost 3.62% (39.78 points) and closed at 1,059.45.

LONDON:
The FTSE index tumbled nearly 8% to stand at 4589 at the close. Banking stocks were hit particularly hard and a total of over £ 93 billion was wiped off the value of British shares.

FRANKFURT:
The DAX index was down 7% to 5387.

PARIS:
The CAC index sank 9% to stand at 3712, its heaviest one-day loss since its creation in 1988.

MOSCOW:
A 15% dive in share value forced yet another halt to Russian trading today.

And these are only the most important ones. There was a downturn in share value everywhere, with not one single example of an economy moving against the trend.

Iceland, a small country with a population of only 250,000, avoided narrowly a complete collapse. Only through a state of emergency and nationalisation of their banks, augmented with the introduction of draconian government powers, did they avoid the risk of becoming a failed state overnight.

The list could go on and on... and I am sure that we will hear more of the same soon.

But do we get any real solutions from our political leaders? Not a word. All they do is throwing a lot of good money after plenty of bad, blowing up the balloon ever more, until it will eventually burst with a bang so loud and large that no-one - not governments and not the banks - will have a leg left to stand on.

Throughout the years of the 'Celtic Tiger' not one bank in Ireland encouraged people to save money. Interest rates for deposits were so low that they actively prevented any real savings. (The only positive exception was the SSIA scheme introduced by Charlie McCreevy, but as it was running for only a limited time, it had only a limited effect.)

But the banks did not only prevent people from saving money, they aggressively encouraged them to spend and borrow ever more, often way beyond prudence and people's real means. Especially young people were heavily targeted by the financial industry, given two or three credit cards and offered 100% mortgages for over-priced houses as well as loans for cars well above their income level and social status.

Above that, the same banks loaned billions to rival property developers, driving them into a hyped-up construction boom that was unsustainable from the very start. The government, and in particular the majority party Fianna Fáil, gave all this its blessing and supported the bubble with very generous tax conditions for the super-rich and the greedy wannabees riding the 'Celtic Tiger'.

Sadly the opposition did not offer any resistance or alternatives either. Even in the 2007 general election campaign Fine Gael pretended that the economy was sound and the country was not facing any financial problems. They could and should have known better, as many analysts warned already of the imminent end of our economic boom.

But Fine Gael leader Enda Kenny (left) and the American consultants who organised his campaign thought that they might lose votes if they mentioned a potential return to harder times. Well, seldom in Irish history was such a crucial strategic mistake made by a party leader.
Had Kenny attacked the government on the grounds of the already shaky economy and the declining financial reserves, he might well be Taoiseach now, with (the then Labour Party leader) Pat Rabbitte as Tánaiste.

And even if they had failed to form a government, they would now at least stand on the moral and political high ground, from which they could attack the incompetent and failing government. However, as things are, the opposition - with the sole exception of Sinn Fein - is caught in the same net of ignorance and complacency that envelopes the government.

One has to wonder if the Green Party is beginning to regret its decision to join the government in 2007. Usually one can see rats leaving a sinking ship, and not jumping onto one. But what is done is done, and so the once proud standard bearers for political and economical alternatives are no more. They have sold their souls and principles for a short-term taste of power, and now they are locked into the rotten system they started out to reform 25 years ago.

Looking around, there is not much hope for changes. Political and economical lifeboats have been burned on the bonfire of our vanities, and now the Irish nation and most of the world - including children, grandchildren and the yet unborn - have to take on a heavy mortgage for the unstable house of capitalism.

There would be ways out of the crisis, and proper solutions, but those who have the power for now are unable and unwilling to even contemplate real alternatives to the capitalist system. Thus we will have no choice but to prepare ourselves for a long and bleak period of collective suffering, while the rich and super-rich who robbed us of a decent future have a good laugh and continue to live in luxury.

The Emerald Islander

04 October 2008

The Cat is out of the Bag

Sean FitzPatrick, chairman of the Anglo Irish Bank and for more than 20 years its chief executive, has openly admitted that his bank - like many other financial institutions in Ireland, Britain, the USA and other parts of the western world - "made serious mistakes". However, he rejected the accusation - made by politicians and media alike - that they had been "reckless".
Speaking with Marian Finucane on RTÉ Radio 1 this morning, FitzPatrick also stated that he is "grateful for the € 400 billion guarantee scheme introduced by the government".
He added that banks would pay the full cost of the guarantee, and the taxpayer would only be called upon "if all the banks fail".

I would not have thought that I ever hear a senior banker make such a statement, and make it in public. It appears that the global financial crisis, which in Ireland's case is first and foremost a massive under-capitalisation of the banks, is more serious than even pessimists expected.

When the chairman of one of the country's major banks mentions the possibility of a failure of all banks on national radio, we all should sit up and listen very carefully.

Until very recently such a sentence would have been seen as economic blasphemy and no-one would have spoken these words, not even behind closed doors, in the cosy clubs and circles where money people meet and socialise.

Now the cat is out of the bag, as we sailors would say, and for everyone to see and hear. Let's hope that there are some sensible people left in government and international finance. Otherwise we might all get a free ride this winter - down to hell in a handcart.

The Emerald Islander

01 October 2008

Mixed Reactions to Ireland's Bank Guarantee

Taoiseach Brian Cowen (on the left), who is currently on a visit to Paris, has said that his 100% bank guarantee scheme has received the full political backing of French President Nicolas Sarkozy (on the right).

Cowen told reporters he thought that President Sarkozy, whose country holds at present the rotating six-month presidency of the EU, "understood precisely" the reasons the Irish government had to act in such a decisive way.

Shares in Irish banks are continuing to recover from their massive losses, after the government's plan to guarantee their deposits and debts has been published.
Dublin's ISEQ index closed 2.5% higher at 3641, with the banking stocks gaining between 8% and 10.5%. They are not out of the woods yet, but the trend begins to look a little more positive.

In London the FTSE closed 1% higher, and other European stocks mainly rallied as well.

Meanwhile, EU Competition Commissioner Neelie Kroes has appealed to national governments "not to act unilaterally" in the current financial crisis, and to consult the commission especially on the question of offering state aid to financial institutions.
Speaking at a press briefing in Brussels, Ms. Kroes said that the EU Commission is in close contact with several governments, including the Irish, but declined to comment on individual cases.

The British government, which has come under pressure from the public and parts of the media to follow Ireland's example, wants the Irish to look closely at their guarantee to make sure it complies with EU law. This is of course a smoke screen. The real reason for British concern is that savers and investors who have their money in British banks might transfer it to Ireland, where it is now absolutely safe, while Britain still guarantees only a sum of £ 20,000.

Prime Minister Gordon Brown (left) said European governments should make sure that whatever actions they took to tackle the global financial crisis complied with EU competition law.

The President of the EU Commission, Jose Manuel Barroso, said that "the EU needs a shake-up of banking deposit insurance schemes", so that there will be more consistency across the Union.

Currently deposit guarantee schemes vary widely across the EU, with some countries offering much greater protection of depositors' savings than others. So far only Ireland has opted for a full 100% guarantee scheme, but it is possible that other countries might follow suit.

The Emerald Islander

30 September 2008

Brian is listening and took David's Advice

In the small hours of last Sunday morning David McWilliams, one of the brightest young analysts and commentators in Ireland, posted a new article on his website.

This article made a bold, but very sensible statement: To get out of the current financial crisis the Irish State should go solo - without waiting for models from other countries - and give a full 100% guarantee for all deposits and loans of Irish banks.

"The only option is to guarantee 100 per cent of all depositors/creditors in the Irish banking system. This guarantee does not extend to shareholders who will have to live with the losses they have suffered. However, it applies to everyone else," McWilliams wrote as the essence of his long and learned article. The complete text can be found on David McWilliams' website under 'Articles' at http://www.davidmcwilliams.ie/

I was probably one of the first people who read this article, right after it was posted online. And I happened also to be the first to leave a comment, at 4:04 am on that Sunday morning.

Then I took the liberty to send a copy of the article to Taoiseach Brian Cowen, Minister for Finance Brian Lenihan and a couple of other ministers who - in my opinion - are able to think for themselves.
Knowing that there was a cabinet meeting scheduled for later that Sunday, I hoped that they might read David’s article beforehand and - maybe - be wise enough to take his advice.

Of course I have no way of knowing if my little initiative helped, if they did read the article before the cabinet meeting, and if it influenced them.

However, the government announcement Minister for Finance Brian Lenihan (left) has made today is exactly what McWilliams advised to do and asked for.

So one could well come to the conclusion that one of the Brians (Lenihan & Cowen) - or someone else in the government - is listening to sound advice. Which means there is some hope after all for Ireland and our economy

Following the biggest drop in share prices the Irish market has ever seen - the ISEQ fell by 13% in one day yesterday, and the especially troubled bank shares dropped between 30% and 45% - this morning's announcement has brought some confidence and stability back to the Dublin stock exchange.

It is early days yet, and the massive financial crisis of the western world is far from over. It will probably even get worse, in particular for the USA, which are now caught in the fast downward spiral all collapsing empires in history have encountered after they overreached themselves and overspent on military adventures and senseless luxuries.

But Ireland might this time get away with only one black eye - metaphorically speaking - if nothing else in our country goes badly wrong.

Following David McWilliams' advice, the government has shown a strong position of leadership and the guarantee of our money by the State is good news for all of us, regardless of wealth and position.

In contrast to programmes initiated elsewhere, this is neither a nationalisation (like the British government's take-over of Northern Rock) nor a bail-out (as attempted by the US administration for Wall Street and rejected by the US Congress yesterday).

This is indeed - as David suggested - an Irish solution for an Irish problem.

The government guarantees the money we have in the banks 100%, but only for two years and not for free. The banks will be charged a fee for this high grade of security (the amount of which is not known yet), so the government creates some extra income for itself. That's rather clever.

And the guarantee is not given willy-nilly to just everyone who happens to have a branch office on the Emerald Isle. Only the six Irish-owned banks will receive the full guarantee, and that is not more than fair. They are: Allied Irish Bank, Bank of Ireland, Anglo-Irish Bank, Irish Life & Permanent, which owns permanent tsb, Irish Nationwide Building Society and the EBS (Educational Building Society).

For all details of the new guarantee rules, and how it affects all banks operating in Ireland, have a look here: http://www.itsyourmoney.ie/index.jsp?1nID=93&2nID=100&nID=153&aID=620

Specific subsidiaries that may be approved by the government following consultations with the Central Bank and the Financial Regulator are also covered under the guarantee.
It also includes all money borrowed by Irish banks from other financial institutions and the statement from the Department of Finance says that all deposits, bonds and debts will now be covered by the State.

Pessimists are already crying 'blue murder' from the roof tops and predict the eventual end of the Republic of Ireland in total state bankruptcy and under a cloud of shame and chaos. Well, in a theoretical way this is quite possible, as much as it is possible that an asteroid falls onto Ireland and makes us all perish in a giant puff of smoke. But realistically you have a better chance to win the Lotto jackpot or even the top prize in the Euro-Millions lottery.

Our bankers - and a lot more so those in the USA - might have been reckless and very greedy in recent years, but they are neither complete fools nor suicidal. So they will recognise what a great and rare gift Brian Lenihan - on the advice of David McWilliams and with backing of Brian Cowen - has bestowed on them. By now they have also realised that they made terrible mistakes, and that they will not have a third chance should they blow this one. So I am with David McWilliams on this, and confident that it will work.

With a little bit luck (of the Irish) thrown in, it might even attract extra money from abroad and perhaps lead to another period of growth and prosperity. By this evening the government will have introduced the necessary legislation in Dáil Éireann, and I can say that I will sleep a lot more sound and confident tonight.

A well-known proverb advises that one should stop digging when finding oneself in a hole. This is - translated into financial terms - exactly what David McWilliams advised on Sunday and Brian Lenihan did today. In fact, it is even a bit more than that. The government is not only telling the banks to stop digging, it is declaring the hole to be a building site.

If we all keep a cool head and use common sense, look out for each other and stick together at all times - hard and easy - the future will be bright again for Ireland in years to come. I am not the kind of person who bestows praise easily, and I have very few heroes. But I want to say today that there is always hope and a future as long as we have people like David McWilliams on the Emerald Isle.

The Emerald Islander